I love Christmas. The family, the food, the kids losing their minds on Christmas morning. But I’ll be honest with you in my line of work, I also see the other side of it. The quiet stress that builds from about now, when the lists get longer and the bank balance doesn’t.
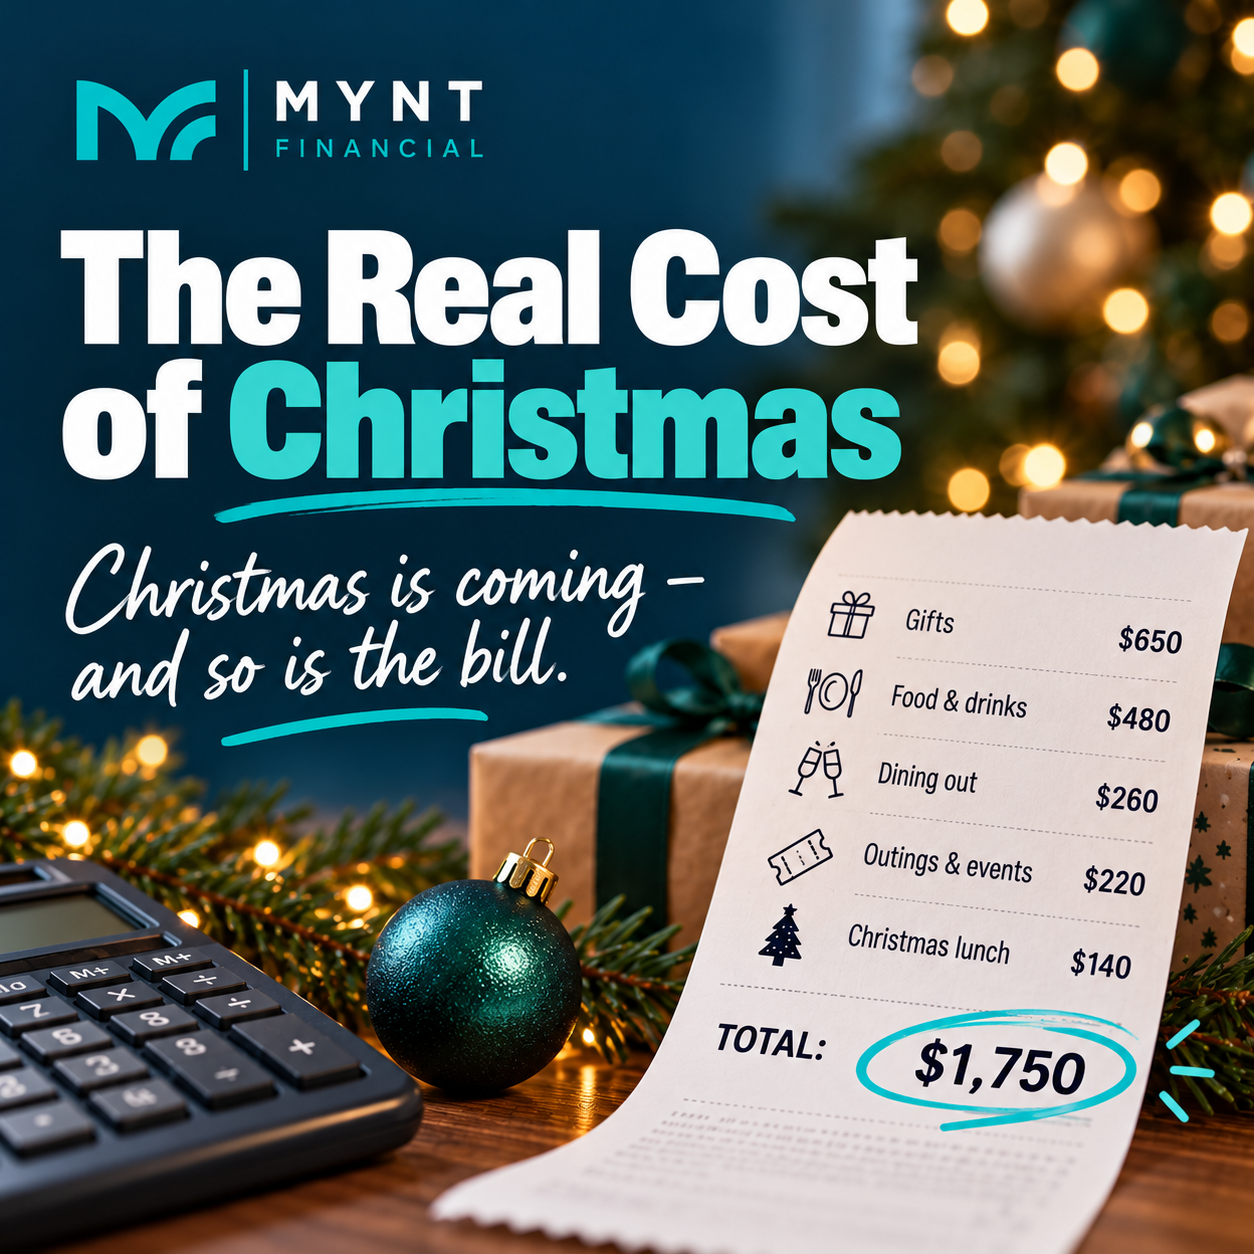
The gifts. The Christmas lunch. The end-of-year breakup dinners, the school concerts, the outings, the trip away. It adds up fast. The latest research found the average Aussie is planned to spend around $1,750 over the festive season on gifts, food, alcohol, dining out and travel. That’s per person, so for a family, you can see how quickly it gets into the thousands.
And this year, it’s landing on households who are already stretched. The Reserve Bank has lifted the cash rate four times in 2026, taking it to 6.60% in September a full 1% higher than where we started the year, and the highest it’s been since 2011. On a $600,000 home loan, that’s roughly $385 a month more in repayments than in January. Add groceries, fuel, insurance and energy bills, and a lot of Aussies are going to feel the pinch this December.
So let’s get ahead of it.
The countdown: 60 days to Christmas
As I write this, there are 60 days until Christmas Day. That’s about eight and a half weeks which is actually great news, because it’s enough time to plan instead of panic.
My tips to keep Christmas under control this year
- Set one number and write it down. Decide your total Christmas budget before you buy a single thing: gifts, food, outings, the lot. Then break it into categories so you know when one is full.
- Start a Christmas “bucket” today. Open a separate savings account and set up a weekly transfer on payday. Whatever’s in it on 20 December is what you spend.
- Do a Kris Kringle. For the extended family or the friend group, one good gift each with a set limit beats ten rushed ones. Most people are relieved when someone suggests it.
- Share the Christmas lunch. Make it a bring-a-plate. The host does the main, everyone else brings a side, a dessert or the drinks. Less cost, less stress, and nobody’s in the kitchen all day.
- Pick your outings. You don’t have to say yes to everything. Choose the two or three events that matter most and skip the rest without guilt.
- Watch the buy now, pay later. It feels painless in December. It isn’t in February, when the instalments land on top of school fees and back-to-school shopping.
- Go easy on the credit card. If you can’t pay it off in full when the statement arrives, you’re paying interest on Christmas well into next year.
- Give time, not just things. A day trip, a beach picnic, a movie night at home. The kids remember the experiences far longer than the presents.
- Check your bills before Christmas, not after. Insurance, rates, school fees, the car rego – know what’s coming in January so it doesn’t blindside you.
A story from last week: they kept the house
Last week, a local agent went out to appraise a family home. Mum, dad, three kids. On paper, a motivated seller – the kind of listing a lot of agents would grab with both hands.
But this couple didn’t want to sell. They were visibly upset. They were under real pressure: a credit card they could only pay the minimum on, a personal loan, council rates that had been due back in September, maintenance on the house, and Christmas coming with three kids. Selling felt like the only way to clear the debt and breathe again.
And they were terrified of what came next. Renting in a tight, competitive market. Staying in the area so the kids didn’t have to change schools. Wondering if they’d ever get back into the market.
This is where I want to give a big shout-out to that agent. Instead of signing them up, he said: “Before you do anything, I want you to have a chat with Josh.” Thank goodness they did.
Where they were
- Home loan of $880,000 at 6.5%
- Credit card of $10,000, only paying the minimum, on a high interest rate
- A personal loan on top
- About $5,000 in bills due within the month (including those overdue rates) that they’d been putting off
- Just $2,500 in savings
The credit card alone was costing them around $175 a month in interest. That means most of their minimum repayment was going straight to the bank, and the balance was barely moving.
What we did
We refinanced their home loan to a new lender at 6.1%, and used some of the equity in their home to clear the credit card, the personal loan and the overdue bills – plus set aside a $10,000 buffer so the next unexpected bill doesn’t become a crisis.
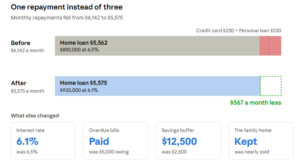
That’s about $567 a month back in their pocket – nearly $6,800 a year. The overdue bills are paid. There’s a $10,000 buffer in the bank. And one simple repayment instead of three.
Here’s the bit I’m proudest of. Rolling short-term debt into a 30-year home loan can cost you more over time if you just leave it there. So we talked it through, and they’re choosing to keep paying close to what they used to. Done that way, the old credit card and personal loan debt is effectively cleared in around five years – not thirty.
Most importantly: they’re keeping their home. The kids stay at their school. No rental applications, no moving boxes, no wondering how they’ll ever buy back in. When we sat down to go through it, the relief on their faces said everything. That’s why I do this job.
Let’s do Christmas without the hangover
Christmas should be about the people around the table, not the bill that turns up in January. So this year, let’s set a budget, stick to it, and not go overboard.
And if you haven’t taken a proper look at your finances in a while – especially with four rate rises this year – now is the time. You might be paying more than you need to on your home loan. You might have debts that are quietly costing you a fortune. Or you might just want someone to sit down with you and look at the whole picture.
That’s what we’re here for. If you’d like a chat to see if we can help you reduce the stress and put you in a better position, give us a call or book a time with me. No pressure, no judgement – just a conversation.
Have a safe and happy festive season.
Feel free to call me directly for a confidential chat – 0402 235 001 or send me a direct Email Josh@myntfinancial.com.au
Cheers, Josh
Director – Mynt Financial
Disclainer: The case study above has been shared with our clients’ permission, and details have been kept general to protect their privacy. Figures are rounded and based on 30-year principal-and-interest loans. This article is general information only and doesn’t take into account your objectives, financial situation or needs. Consider whether it’s right for you and seek advice before making any decision. Lending criteria, fees and charges apply.